.For many young people in Portugal, buying their first home has become a challenge not only because of real estate prices, but also because of the need to save a significant amount for a down payment.
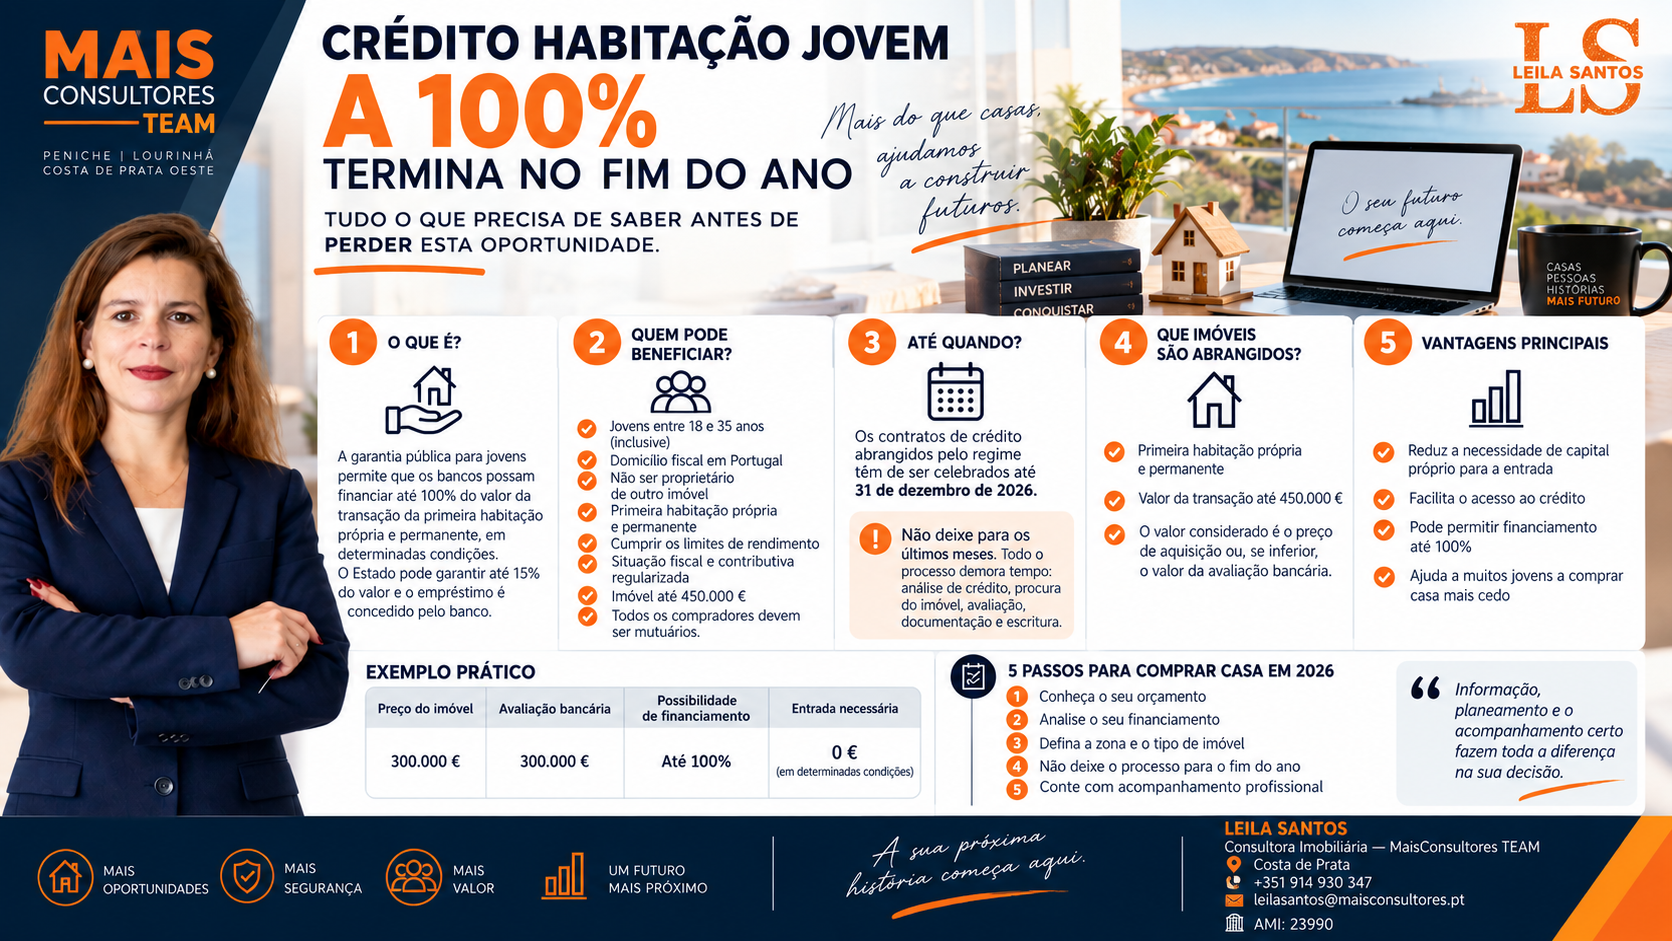
The public guarantee for home loans for young people has changed this scenario, allowing banks—under certain conditions—to finance up to 100% of the purchase price of a first permanent home.
But there is an important date on the calendar: December 31, 2026.
If you’re thinking about buying a home and are 35 or younger, now is the right time to understand how this measure works, what the requirements are, and what you should do before moving forward.
What is the public guarantee for young people?
The public guarantee is a measure that allows the government to provide a guarantee to the bank, which can facilitate access to a large loan for the purchase of a first permanent home.
In practice, the measure allows financing to range from 85% to 100% of the property’s transaction value, provided the specified conditions are met and the bank approves the loan.
It is important to clarify a misconception often associated with this measure:
“100% loan” does not mean a home provided by the government.
The loan is still granted by a bank, and the buyer remains responsible for paying the principal, interest, and other charges.
The public guarantee serves as additional protection for the bank and may cover up to 15% of the transaction value.
Who is eligible?
The program is generally intended for young people between the ages of 18 and 35, inclusive, who meet the requirements defined for the program.
Among the conditions are:
- Have tax residency in Portugal;
- Be 35 years old or younger;
- Not owning another residential property;
- Intending to purchase one’s first permanent home;
- Meeting the applicable income limits;
- Have their tax and social security obligations in good standing;
- The transaction value of the property must not exceed 450,000 euros;
- All buyers must be borrowers and meet the eligibility requirements.
In addition to these conditions, there is another key point: the bank continues to conduct its own risk assessment.
In other words, meeting the requirements for the public guarantee does not mean that the loan will be automatically approved.
How long can this measure be used?
This is one of the most important questions for anyone planning to buy a home.
Currently, loan agreements covered by the public guarantee must be entered into by December 31, 2026.
This means that it’s not enough to start looking for a home at the end of the year.
You need to consider the entire process:
- Assess your financial capacity;
- Obtain pre-approval or loan approval;
- Search for a suitable property;
- Make an offer;
- Complete the bank appraisal;
- Handle the documentation;
- Formalize the loan agreement within the applicable deadline.
Therefore, anyone wishing to benefit from this measure should avoid leaving the entire process until the last few months.
The property must also meet certain requirements
It is not enough for the buyer to be eligible.
The property purchased under this program must be intended as a first, owner-occupied, permanent residence, and the transaction value cannot exceed 450,000 euros.
There is also an important detail: for the purposes of the program, the transaction value corresponds to the purchase price or, if lower, to the appraised value at the time the contract is signed.
This makes the bank’s appraisal particularly important.
A simple example
Imagine you find a house for 300,000 €.
If the bank’s appraisal is also 300,000 €, and provided all other requirements are met and the bank approves the loan, you may be able to finance up to the total transaction value.
But if the property is purchased for 300,000 € and the bank’s appraisal is lower, the financing situation may be different.
Therefore, a property’s listed price should not be analyzed in isolation.
The biggest benefit: lowering the barrier to entry
For many young people, the main obstacle to buying a home isn’t necessarily the monthly payment.
It’s coming up with the necessary down payment to move forward with the purchase.
A high loan-to-value ratio can significantly reduce the amount of down payment required for the purchase, although there are always costs and conditions to consider.
It’s essential to do the math before making any commitment.
Among the factors to analyze are:
- Monthly payment;
- Interest rate;
- Loan term;
- Insurance;
- Bank fees;
- Taxes and other applicable costs;
- Expenses related to the purchase;
- Available financial margin after the purchase.
A government guarantee can facilitate access to credit, but it does not eliminate the need for responsible financial analysis.
5 Steps for Those Looking to Buy a Home in 2026
If you’re 35 or younger and thinking about buying your first home, start by getting organized.
1. Know your budget
Before looking for properties, figure out how much you can actually afford to pay each month.
2. Conduct a financing analysis
Compare offers and determine how much you can qualify for.
3. Decide on a location and property type
On the Silver Coast, for example, there are different markets, prices, and property types. Having clear criteria helps you avoid wasting time on properties that don’t fit your budget.
4. Don’t put off the process until the end of the year
The December 31, 2026, deadline makes planning particularly important.
5. Seek professional guidance
Buying a home involves financial decisions, paperwork, negotiation, and evaluating the property itself.
Having the right real estate and financial guidance can help make the process more organized and transparent.
And after 2026?
The date currently set for the signing of contracts covered by the program is December 31, 2026.
Any future changes to the program should be monitored through official sources.
Therefore, anyone who currently meets the eligibility requirements and intends to buy their first home should not assume that the program will remain available after this date under the same conditions.
More important than acting on impulse is starting to prepare the process now.
Buying a home should be an informed decision, based on careful calculations and a clear understanding of the specific financing terms.
Need help with this topic?
Leila Santos
Real Estate Consultant — MaisConsultores TEAM
📍 Silver Coast
📱 +351 914 930 347
✉️ leilasantos@maisconsultores.pt
🏢 AMI: 23990
👉 Contact me for a no-obligation consultation.